 AIA Global Power Multi-Currency Plan 3 (Participating Savings): 9 Currencies & 0.31% vs. 6.5% IRR AuditVS
 BOC Life Deferred Annuity (Fixed Term) QDAP: 100% Guaranteed 3.10%–3.30% IRR Audit
Multi-Currency Participating Savings (AIA Global Power 3) vs. 100%-Guaranteed QDAP (BOC Life)
Resolves the most common Hong Kong savings-policy trade-off: 0.31% guaranteed / 6.5% projected multi-currency savings (zero tax relief, >80%–97% non-guaranteed) vs. 3.10%–3.30% contractual guaranteed IRR + HK$60,000 tax deduction.
Last verified: 2026-11-20 · Official policy wordings and trustee disclosures always prevail.
Key Takeaways
- Clear priority order for 15%–17% HK taxpayers: BOC Life Fixed-Term QDAP locks in 3.10%–3.30% contractual guaranteed IRR plus up to HK$10,200/yr in tax relief — far higher certainty than non-deductible participating savings.
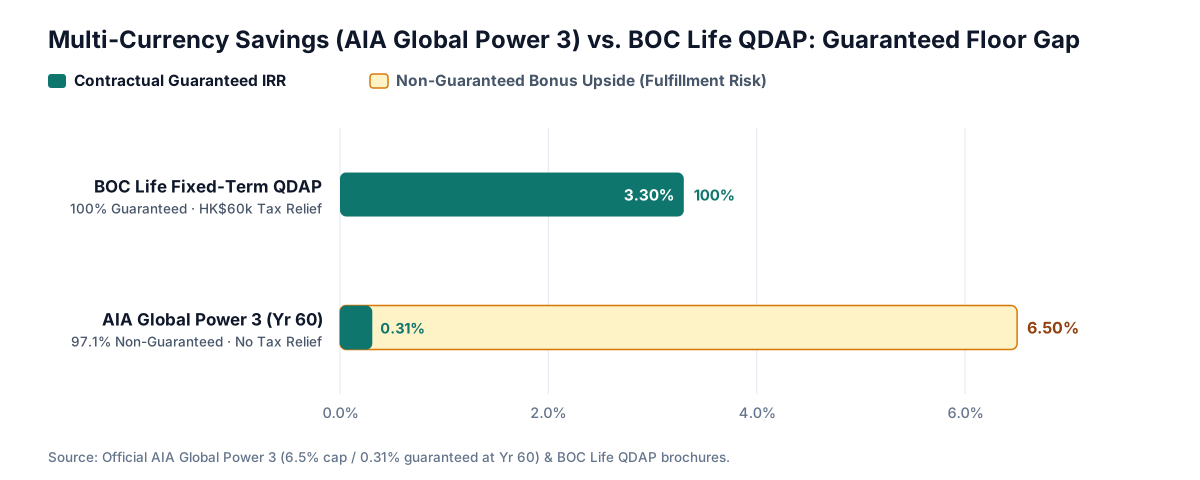
- Night-and-day contractual floor: on AIA Global Power 3's official US$50,000 example, Year-30 guaranteed value is just US$51,167 (0.31% guaranteed IRR by Year 60), relying on 0%–75% growth assets for upside.
- Consider multi-currency participating savings only after exhausting tax-deductible VHIS/TVC/QDAP allowances and only with genuine 20+ year surplus capital.
Visual Comparison
Clause-by-Clause Matrix
Hong Kong's flagship long-horizon multi-currency participating savings plan: up to 9 currencies, Policy Split, and Bonus Lock-in/Unlock; official brochure's 5Y USD example reveals >80% (Yr 30) and >97% (Yr 60) of projected value is non-guaranteed (0.31% guaranteed IRR floor vs. 6.5% capped projection).
Rare 100%-guaranteed Hong Kong QDAP: 5-year premium payment with 10 years of 100% guaranteed monthly annuity income — official brochure lists 3.10% (15Y) to 3.30% (25Y/30Y) annualized guaranteed IRR in HKD or USD with zero dividend fulfillment risk.
Families with ample liquid reserves planning 20–30+ year multi-currency legacy or overseas-education funding who knowingly accept high non-guaranteed bonus volatility.
15%–17% bracket taxpayers prioritising contractual guaranteed IRR over volatile non-guaranteed dividend projections.
9 Currencies & Policy Split:Up to 9 currencies (USD, HKD, RMB, GBP, AUD, CAD, EUR, SGD, plus MOP for Macau policies) with Currency Exchange, Policy Split, and Bonus Lock-in & Unlock options (projected returns differ by currency). | Official 5Y USD Example (US$50,000 Paid):Projected breakeven at Year 8 (non-guaranteed); Year 30 projected surrender US$260,138 (Guaranteed US$51,167 vs. Non-Guaranteed US$208,971 = 80.3%); Year 60 projected US$1,936,279 (Guaranteed US$57,055 vs. Non-Guaranteed US$1,879,224 = 97.1%); projected IRR capped at 6.5% vs. 0.31% guaranteed IRR floor. | Target Asset Mix (High Growth Allocation):25%–100% bonds and fixed income; 0%–75% growth assets (listed equities, equity funds, real estate, private equity, private credit), dynamically adjusted across interest-rate cycles. | Payment Terms & Liquidity Lock:Single, 3-year (limited offer), 5-year, and 10-year payment terms; brochure warns early surrender causes heavy losses and single-pay policies face higher bonus volatility than multi-year pay.
Payment & Annuity Structure:Fixed 5-year premium payment term with 15/20/25/30-year policy terms (paying 10 years of Guaranteed Monthly Annuity Income starting after the 5th/10th/15th/20th policy anniversary). | Official Annual-Pay Guaranteed IRR at Maturity:Identical in HKD and USD: 3.10% (15Y), 3.20% (20Y), 3.30% (25Y), and 3.30% (30Y) for annual payment (RMB 2.00%–2.38%; non-annual HKD/USD 2.70%–3.25%). | Non-Guaranteed Component & Liquidity Risk:Monthly cash-out annuity stream is 100% guaranteed (only optional accumulation interest is non-guaranteed); subject to BOC Life credit risk and steep early surrender losses.
Combines 9 currencies, Policy Split, and both Bonus Lock-in and Unlock for multi-child education or cross-border legacy planning. · Explicitly discloses the 0.31% guaranteed IRR floor alongside the 6.5% capped projection for transparent stress-testing.
3.10%–3.30% pure guaranteed IRR before factoring in up to HK$10,200/yr salaries tax savings (at 17% marginal rate). · Eliminates dividend fulfillment ratio uncertainty on the monthly annuity stream.
Not a QDAP (zero HK$60,000 tax deduction), and >80% of Year-30 projected value is non-guaranteed — never treat participating savings as a bank deposit substitute. · Surrendering in the first 7–8 years results in capital loss; exercising Currency Exchange recalculates future bonuses on the target currency's scale.
Non-annual payment modes cut guaranteed IRR noticeably (e.g. 2.70%–2.94% on 15Y vs. 3.10% annual); pay annually if cash flow permits. · Shares the HK$60,000 annual deduction cap with MPF TVC — avoid over-allocating beyond unused tax headroom.
| Clause-by-Clause Matrix | AIA Global Power Multi-Currency Plan 3 (Participating Savings): 9 Currencies & 0.31% vs. 6.5% IRR Audit | BOC Life Deferred Annuity (Fixed Term) QDAP: 100% Guaranteed 3.10%–3.30% IRR Audit |
|---|---|---|
| Overview | Hong Kong's flagship long-horizon multi-currency participating savings plan: up to 9 currencies, Policy Split, and Bonus Lock-in/Unlock; official brochure's 5Y USD example reveals >80% (Yr 30) and >97% (Yr 60) of projected value is non-guaranteed (0.31% guaranteed IRR floor vs. 6.5% capped projection). | Rare 100%-guaranteed Hong Kong QDAP: 5-year premium payment with 10 years of 100% guaranteed monthly annuity income — official brochure lists 3.10% (15Y) to 3.30% (25Y/30Y) annualized guaranteed IRR in HKD or USD with zero dividend fulfillment risk. |
| Best Suited For | Families with ample liquid reserves planning 20–30+ year multi-currency legacy or overseas-education funding who knowingly accept high non-guaranteed bonus volatility. | 15%–17% bracket taxpayers prioritising contractual guaranteed IRR over volatile non-guaranteed dividend projections. |
| Verified Clauses & Rates | 9 Currencies & Policy Split:Up to 9 currencies (USD, HKD, RMB, GBP, AUD, CAD, EUR, SGD, plus MOP for Macau policies) with Currency Exchange, Policy Split, and Bonus Lock-in & Unlock options (projected returns differ by currency). | Official 5Y USD Example (US$50,000 Paid):Projected breakeven at Year 8 (non-guaranteed); Year 30 projected surrender US$260,138 (Guaranteed US$51,167 vs. Non-Guaranteed US$208,971 = 80.3%); Year 60 projected US$1,936,279 (Guaranteed US$57,055 vs. Non-Guaranteed US$1,879,224 = 97.1%); projected IRR capped at 6.5% vs. 0.31% guaranteed IRR floor. | Target Asset Mix (High Growth Allocation):25%–100% bonds and fixed income; 0%–75% growth assets (listed equities, equity funds, real estate, private equity, private credit), dynamically adjusted across interest-rate cycles. | Payment Terms & Liquidity Lock:Single, 3-year (limited offer), 5-year, and 10-year payment terms; brochure warns early surrender causes heavy losses and single-pay policies face higher bonus volatility than multi-year pay. | Payment & Annuity Structure:Fixed 5-year premium payment term with 15/20/25/30-year policy terms (paying 10 years of Guaranteed Monthly Annuity Income starting after the 5th/10th/15th/20th policy anniversary). | Official Annual-Pay Guaranteed IRR at Maturity:Identical in HKD and USD: 3.10% (15Y), 3.20% (20Y), 3.30% (25Y), and 3.30% (30Y) for annual payment (RMB 2.00%–2.38%; non-annual HKD/USD 2.70%–3.25%). | Non-Guaranteed Component & Liquidity Risk:Monthly cash-out annuity stream is 100% guaranteed (only optional accumulation interest is non-guaranteed); subject to BOC Life credit risk and steep early surrender losses. |
| Strengths | Combines 9 currencies, Policy Split, and both Bonus Lock-in and Unlock for multi-child education or cross-border legacy planning. · Explicitly discloses the 0.31% guaranteed IRR floor alongside the 6.5% capped projection for transparent stress-testing. | 3.10%–3.30% pure guaranteed IRR before factoring in up to HK$10,200/yr salaries tax savings (at 17% marginal rate). · Eliminates dividend fulfillment ratio uncertainty on the monthly annuity stream. |
| Watch-Outs Before Deciding | Not a QDAP (zero HK$60,000 tax deduction), and >80% of Year-30 projected value is non-guaranteed — never treat participating savings as a bank deposit substitute. · Surrendering in the first 7–8 years results in capital loss; exercising Currency Exchange recalculates future bonuses on the target currency's scale. | Non-annual payment modes cut guaranteed IRR noticeably (e.g. 2.70%–2.94% on 15Y vs. 3.10% annual); pay annually if cash flow permits. · Shares the HK$60,000 annual deduction cap with MPF TVC — avoid over-allocating beyond unused tax headroom. |
Sources
- AIA Hong Kong: Global Power Multi-Currency Plan 3 Brochure PDF (AIA Hong Kong, Last verified: 2026-11-20)
- AIA Hong Kong: Official Fulfillment Ratio & TCV Ratio Disclosure (AIA Hong Kong, Last verified: 2026-11-20)
- BOC Life: Deferred Annuity (Fixed Term) Official Product Brochure PDF (BOC Life, Last verified: 2026-11-20)
CoverHK · Multi-Currency Participating Savings (AIA Global Power 3) vs. 100%-Guaranteed QDAP (BOC Life)
Want a tailored clause check or exact numbers?
Share your age band, existing corporate medical cover, or current MPF trustee — we will reply in writing with a clear side-by-side summary.