VHIS Standard vs. Flexi Semi-Private Deductible: 7 Clauses That Decide Real Claims
Skip generic star ratings. Compare surgical fee structures, room-upgrade adjustment penalties, unknown pre-existing lookbacks, and retirement deductible reduction options across Hong Kong VHIS tiers.
Key Takeaways
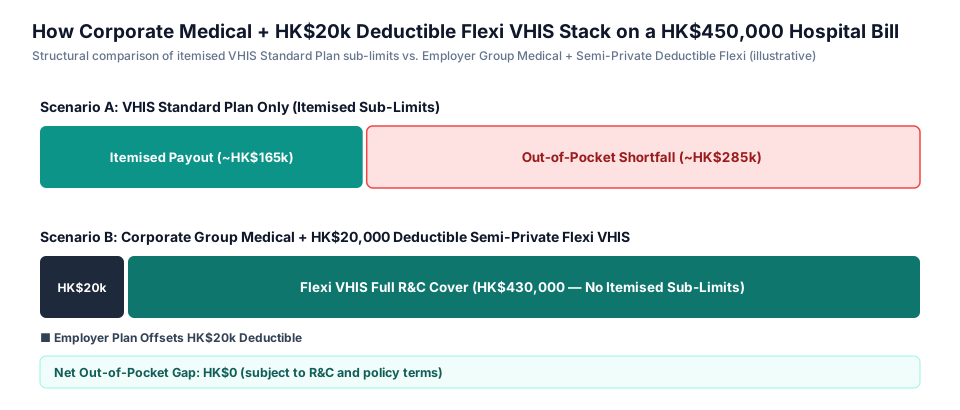
- Standard Plans reimburse against itemised sub-limits, leaving gaps on major surgery and targeted cancer care; Flexi full-cover plans reimburse actual R&C charges above the deductible.
- If you hold corporate group medical cover, a HK$20,000–HK$50,000 deductible Flexi semi-private plan keeps premiums manageable while protecting against large bills.
- Always verify three fine-print clauses before buying: room-upgrade adjustment factors, unknown pre-existing waiting periods, and guaranteed no-underwriting deductible reduction at retirement.
Last verified: 2026-11-19 · Official policy wordings and trustee disclosures always prevail.
Side-by-Side Clause Comparison of Both VHIS Structures
| Plan | Annual Limit | Surgical Fee Structure | Non-Surgical Cancer Treatment | Prescribed Diagnostic Imaging |
|---|---|---|---|---|
| HK$420,000 | Tiered surgical schedule (Complex HK$50,000 / Major HK$25,000 / Intermediate HK$12,500 / Minor HK$5,000) plus 35% anaesthetist & 35% operating theatre caps | Prescribed non-surgical cancer treatments (radiotherapy, chemo, targeted, immunotherapy): HK$80,000/year | Prescribed diagnostic imaging (CT / MRI / PET): HK$20,000/year limit with 30% co-insurance | |
| HK$8,000,000 | Replaces the tiered surgical table with full reimbursement subject to 'Reasonable & Customary' (R&C) charges — check pre-authorisation rules | Typically reimbursed in full up to the annual limit after deductible; verify targeted drugs, immunotherapy, and take-home oral chemotherapy clauses | Most full-cover Flexi plans waive the 30% co-insurance above the deductible — verify whether standalone outpatient imaging is included |
7 Clause Questions to Verify Before Signing Any VHIS Policy
- Does the plan follow the statutory 0%/25%/50%/100% unknown pre-existing schedule, or shorten it to Day 31 / Year 2?
- If you voluntarily upgrade from Semi-Private to Private ward, what adjustment factor reduces the entire claim (often 50%)?
- At which exact ages can you lower or remove the annual deductible without medical re-underwriting when leaving corporate cover?
- Is the 30% co-insurance waived for standalone outpatient CT / MRI / PET scans, or only inpatient scans?
- Does non-surgical cancer cover explicitly include targeted drugs, immunotherapy, and take-home oral chemotherapy?
- Is there a lifetime cap on top of the annual limit, and does it apply only to the Flexi enhancement layer?
- What do the insurer's published standard age-band premiums look like at ages 60, 70, and 80?
Sources
- Health Bureau: VHIS Standard Plan vs. Flexi Plan (Health Bureau (HKSAR), Last verified: 2026-11-19)
- Health Bureau: Official List of Certified VHIS Plans (Health Bureau (HKSAR), Last verified: 2026-11-19)
Frequently Asked Questions
Do high-deductible Flexi VHIS plans still qualify for the HK$8,000 tax deduction?
Yes. As long as the plan is a Health Bureau-certified VHIS Flexi plan, its qualifying VHIS premium (excluding any non-VHIS riders) counts toward the HK$8,000/yr deduction cap per insured person.
CoverHK Monthly Clause & Fee Brief
Track HK VHIS premium revisions, MPF FER shifts, and new policy teardowns
One or two concise emails per month anchored to official filings — zero sales spam.
CoverHK · VHIS Standard vs. Flexi Semi-Private Deductible: 7 Clauses That Decide Real Claims
Want a tailored clause check or exact numbers?
Share your age band, existing corporate medical cover, or current MPF trustee — we will reply in writing with a clear side-by-side summary.