 Bowtie Pink VHIS Plan (Semi-Private Room - HKD20,000 Deductible)VS
 AXA WiseGuard Pro Medical Insurance Plan (Regular (HKD20,000 Deductible))
Bowtie Pink Semi-Private (HK$20k) vs. AXA WiseGuard Pro Regular (HK$20k)
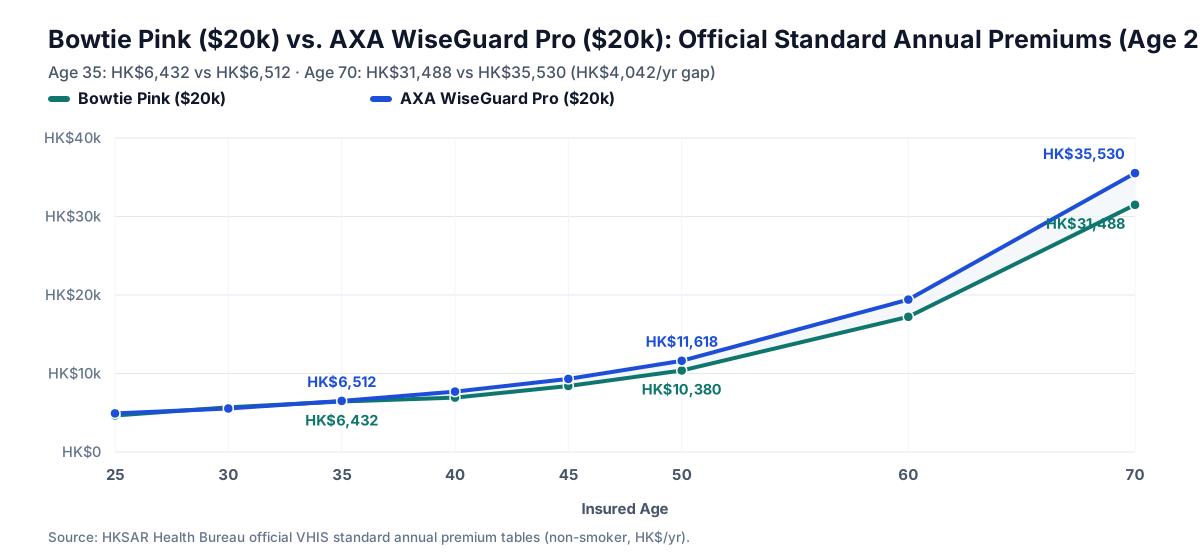
Identical HK$20,000 deductible and near-identical Age-35 price (HK$6,432 vs. HK$6,512), yet sharply different contract design: HK$10M/HK$50M lifetime vs. HK$5M/no lifetime cap, Day-1 vs. 90-day unknown pre-existing cover, and suite-upgrade penalties.
Last verified: 2026-11-20 · Official policy wordings and trustee disclosures always prevail.
Key Takeaways
- Day-1 unknown pre-existing & outpatient visits: AXA WiseGuard Pro covers unknown pre-existing conditions from Day 1 (vs. 90-day wait on Bowtie Pink) with unlimited prior 30-day and follow-up 90-day visits (vs. 2 prior / 5 follow-up on Bowtie Pink).
- Limit design & psychiatric: AXA removes the lifetime cap but sets a HK$5M annual cap and HK$30,000/yr psychiatric sub-limit; Bowtie Pink doubles the annual limit to HK$10M with uncapped psychiatric cover, subject to a HK$50M lifetime cap.
- Suite-upgrade penalty & age-70 cost: voluntarily upgrading above Standard Private drops AXA's enhanced benefit factor to 0% (Standard floor only) vs. 25% on Bowtie Pink; age-70 standard annual premiums are HK$31,488 vs. HK$35,530.
Visual Comparison
Clause-by-Clause Matrix
Semi-Private Room (full cover without itemised sub-limits)
Semi-Private Room (Regular full cover, no lifetime benefit limit)
HK$0 / HK$20,000 / HK$50,000 / HK$80,000
HK$0 / HK$20,000 / HK$50,000
Complex surgeon fee limit: no itemised dollar limit; SMM benefit: -.
Complex surgeon fee limit: no itemised dollar limit; SMM benefit: -.
0% for first 90 days of Policy Year 1; 100% full cover from Day 91 onwards (far shorter than Standard Plan Year 4)
Full cover from Day 1 for unknown pre-existing conditions (no 30-day or 90-day waiting period)
Limit: no itemised dollar limit; co-insurance: N.A. (subject to applicable deductible).
Limit: no itemised dollar limit; co-insurance: N.A. (subject to applicable deductible).
Prescribed non-surgical cancer treatment limit: no itemised dollar limit (subject to annual limit and R&C charges).
Prescribed non-surgical cancer treatment limit: no itemised dollar limit (subject to annual limit and R&C charges).
Voluntary upgrade to Standard Private Room: 50% adjustment factor; above Standard Private (suite/VIP): 25% factor (floored at Standard Plan limits; waived for involuntary emergency/isolation)
Voluntary upgrade from Semi-Private to Standard Private: 50% adjustment factor on variable benefits; above Standard Private (suite/VIP): 0% factor on enhanced benefits (falls back to Standard floor)
Hong Kong inpatient psychiatric limit: no itemised dollar limit.
Hong Kong inpatient psychiatric limit: $30,000.
| Clause-by-Clause Matrix | Bowtie Pink VHIS Plan (Semi-Private Room - HKD20,000 Deductible) | AXA WiseGuard Pro Medical Insurance Plan (Regular (HKD20,000 Deductible)) |
|---|---|---|
| Ward Class | Semi-Private Room (full cover without itemised sub-limits) | Semi-Private Room (Regular full cover, no lifetime benefit limit) |
| Annual Limit | HK$10,000,000 | HK$5,000,000 |
| Lifetime Limit | HK$50,000,000 | No lifetime limit |
| Age 35 Std Annual Premium | HK$6,432 / yr | HK$6,512 / yr |
| Age 50 Std Annual Premium | HK$10,380 / yr | HK$11,618 / yr |
| Age 70 Std Annual Premium | HK$31,488 / yr | HK$35,530 / yr |
| Deductible Options | HK$0 / HK$20,000 / HK$50,000 / HK$80,000 | HK$0 / HK$20,000 / HK$50,000 |
| Surgical Fee Structure | Complex surgeon fee limit: no itemised dollar limit; SMM benefit: -. | Complex surgeon fee limit: no itemised dollar limit; SMM benefit: -. |
| Unknown Pre-Existing Conditions | 0% for first 90 days of Policy Year 1; 100% full cover from Day 91 onwards (far shorter than Standard Plan Year 4) | Full cover from Day 1 for unknown pre-existing conditions (no 30-day or 90-day waiting period) |
| Prescribed Diagnostic Imaging | Limit: no itemised dollar limit; co-insurance: N.A. (subject to applicable deductible). | Limit: no itemised dollar limit; co-insurance: N.A. (subject to applicable deductible). |
| Non-Surgical Cancer Treatment | Prescribed non-surgical cancer treatment limit: no itemised dollar limit (subject to annual limit and R&C charges). | Prescribed non-surgical cancer treatment limit: no itemised dollar limit (subject to annual limit and R&C charges). |
| Room-Upgrade Co-Insurance | Voluntary upgrade to Standard Private Room: 50% adjustment factor; above Standard Private (suite/VIP): 25% factor (floored at Standard Plan limits; waived for involuntary emergency/isolation) | Voluntary upgrade from Semi-Private to Standard Private: 50% adjustment factor on variable benefits; above Standard Private (suite/VIP): 0% factor on enhanced benefits (falls back to Standard floor) |
| Psychiatric Inpatient | Hong Kong inpatient psychiatric limit: no itemised dollar limit. | Hong Kong inpatient psychiatric limit: $30,000. |
CoverHK · Bowtie Pink Semi-Private (HK$20k) vs. AXA WiseGuard Pro Regular (HK$20k)
Want a tailored clause check or exact numbers?
Share your age band, existing corporate medical cover, or current MPF trustee — we will reply in writing with a clear side-by-side summary.