 BOC Life Deferred Annuity (Fixed Term) QDAP: 100% Guaranteed 3.10%–3.30% IRR AuditVS
 HSBC Life Deferred Income Goal (QDAP): HKD & USD Guaranteed vs. Projected IRR Audit
BOC Life Fixed-Term QDAP vs. HSBC Income Goal QDAP: Hong Kong Bank Annuity Showdown
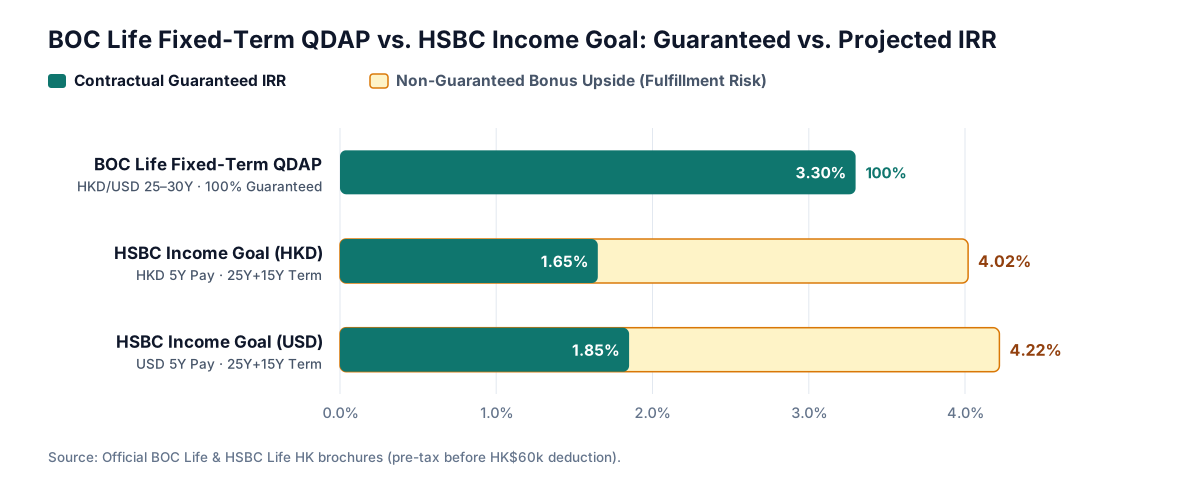
Hong Kong's two major bank-channel QDAPs side by side: BOC Life's 100% guaranteed 3.10%–3.30% HKD/USD IRR vs. HSBC Income Goal's 0.94%–1.65% guaranteed / 3.82%–4.02% projected HKD IRR (up to 4.22% USD).
Last verified: 2026-11-20 · Official policy wordings and trustee disclosures always prevail.
Key Takeaways
- BOC Life wins on certainty: 3.10% (15Y) to 3.30% (25Y–30Y) pure guaranteed IRR in HKD or USD with zero bonus volatility.
- HSBC targets dividend upside via 0%–40% growth assets (projected 3.82%–4.02% HKD / 3.97%–4.22% USD), but guaranteed IRR is only 0.94%–1.85% with nearly half of long-term monthly payouts non-guaranteed.
- For taxpayers seeking a bond-like tax-deductible floor, BOC Life's 100% guarantee is far more predictable; HSBC only makes sense if you knowingly accept multi-decade dividend fulfillment risk.
Visual Comparison
Clause-by-Clause Matrix
Rare 100%-guaranteed Hong Kong QDAP: 5-year premium payment with 10 years of 100% guaranteed monthly annuity income — official brochure lists 3.10% (15Y) to 3.30% (25Y/30Y) annualized guaranteed IRR in HKD or USD with zero dividend fulfillment risk.
Audited from HSBC Life's June 2024 brochure: 5/10-year pay with 10–25Y accumulation and 10–20Y payout; headline projected total IRR reaches 4.02% HKD / 4.22% USD, but guaranteed IRR is only 0.94%–1.65% HKD / 1.05%–1.85% USD.
15%–17% bracket taxpayers prioritising contractual guaranteed IRR over volatile non-guaranteed dividend projections.
HSBC banking clients comfortable taking 0%–40% growth-asset dividend risk over 20–40 year horizons for higher projected total IRR.
Payment & Annuity Structure:Fixed 5-year premium payment term with 15/20/25/30-year policy terms (paying 10 years of Guaranteed Monthly Annuity Income starting after the 5th/10th/15th/20th policy anniversary). | Official Annual-Pay Guaranteed IRR at Maturity:Identical in HKD and USD: 3.10% (15Y), 3.20% (20Y), 3.30% (25Y), and 3.30% (30Y) for annual payment (RMB 2.00%–2.38%; non-annual HKD/USD 2.70%–3.25%). | Non-Guaranteed Component & Liquidity Risk:Monthly cash-out annuity stream is 100% guaranteed (only optional accumulation interest is non-guaranteed); subject to BOC Life credit risk and steep early surrender losses.
Official Guaranteed IRR (5Y Pay, Unisex/All Ages):10Y accum + 10Y payout: HKD 0.94%–1.10% / USD 1.05%–1.20%; 15+15Y: HKD 1.21%–1.30% / USD 1.35%–1.45%; 20+20Y: HKD 1.33%–1.40% / USD 1.54%–1.60%; 25+15Y: HKD 1.60%–1.65% / USD 1.79%–1.85%. | Official Projected Total IRR (100% Fulfillment Assumed):10+10Y: HKD 3.82%–3.88% / USD 3.97%–4.02%; 15+15Y: HKD 3.86%–3.90% / USD 4.01%–4.05%; 20+20Y: HKD 3.97%–4.00% / USD 4.18%–4.20%; 25+15Y: HKD 3.99%–4.02% / USD 4.20%–4.22%. | Asset Mix & Dividend Dependency:60%–100% fixed income and 0%–40% growth assets; in the 25+15Y HKD example, nearly half of the HK$11,006 monthly payout (HK$5,492) is non-guaranteed — making realised IRR heavily reliant on dividend fulfillment.
3.10%–3.30% pure guaranteed IRR before factoring in up to HK$10,200/yr salaries tax savings (at 17% marginal rate). · Eliminates dividend fulfillment ratio uncertainty on the monthly annuity stream.
Available in both HKD and USD with identical published IRR bands across issue ages, gender, and smoking status. · Projected total IRR up to 4.22% (USD) ranks toward the upper end among Hong Kong bank-channel QDAPs.
Non-annual payment modes cut guaranteed IRR noticeably (e.g. 2.70%–2.94% on 15Y vs. 3.10% annual); pay annually if cash flow permits. · Shares the HK$60,000 annual deduction cap with MPF TVC — avoid over-allocating beyond unused tax headroom.
Spread between guaranteed IRR (0.94%–1.65% HKD) and projected total IRR (3.82%–4.02%) exceeds 2.3% — always stress-test at 60%/80% fulfillment. · If weak markets cut non-guaranteed bonuses by half, realised IRR can finish well behind BOC Life Fixed Term's 3.10%–3.30% guaranteed floor.
| Clause-by-Clause Matrix | BOC Life Deferred Annuity (Fixed Term) QDAP: 100% Guaranteed 3.10%–3.30% IRR Audit | HSBC Life Deferred Income Goal (QDAP): HKD & USD Guaranteed vs. Projected IRR Audit |
|---|---|---|
| Overview | Rare 100%-guaranteed Hong Kong QDAP: 5-year premium payment with 10 years of 100% guaranteed monthly annuity income — official brochure lists 3.10% (15Y) to 3.30% (25Y/30Y) annualized guaranteed IRR in HKD or USD with zero dividend fulfillment risk. | Audited from HSBC Life's June 2024 brochure: 5/10-year pay with 10–25Y accumulation and 10–20Y payout; headline projected total IRR reaches 4.02% HKD / 4.22% USD, but guaranteed IRR is only 0.94%–1.65% HKD / 1.05%–1.85% USD. |
| Best Suited For | 15%–17% bracket taxpayers prioritising contractual guaranteed IRR over volatile non-guaranteed dividend projections. | HSBC banking clients comfortable taking 0%–40% growth-asset dividend risk over 20–40 year horizons for higher projected total IRR. |
| Verified Clauses & Rates | Payment & Annuity Structure:Fixed 5-year premium payment term with 15/20/25/30-year policy terms (paying 10 years of Guaranteed Monthly Annuity Income starting after the 5th/10th/15th/20th policy anniversary). | Official Annual-Pay Guaranteed IRR at Maturity:Identical in HKD and USD: 3.10% (15Y), 3.20% (20Y), 3.30% (25Y), and 3.30% (30Y) for annual payment (RMB 2.00%–2.38%; non-annual HKD/USD 2.70%–3.25%). | Non-Guaranteed Component & Liquidity Risk:Monthly cash-out annuity stream is 100% guaranteed (only optional accumulation interest is non-guaranteed); subject to BOC Life credit risk and steep early surrender losses. | Official Guaranteed IRR (5Y Pay, Unisex/All Ages):10Y accum + 10Y payout: HKD 0.94%–1.10% / USD 1.05%–1.20%; 15+15Y: HKD 1.21%–1.30% / USD 1.35%–1.45%; 20+20Y: HKD 1.33%–1.40% / USD 1.54%–1.60%; 25+15Y: HKD 1.60%–1.65% / USD 1.79%–1.85%. | Official Projected Total IRR (100% Fulfillment Assumed):10+10Y: HKD 3.82%–3.88% / USD 3.97%–4.02%; 15+15Y: HKD 3.86%–3.90% / USD 4.01%–4.05%; 20+20Y: HKD 3.97%–4.00% / USD 4.18%–4.20%; 25+15Y: HKD 3.99%–4.02% / USD 4.20%–4.22%. | Asset Mix & Dividend Dependency:60%–100% fixed income and 0%–40% growth assets; in the 25+15Y HKD example, nearly half of the HK$11,006 monthly payout (HK$5,492) is non-guaranteed — making realised IRR heavily reliant on dividend fulfillment. |
| Strengths | 3.10%–3.30% pure guaranteed IRR before factoring in up to HK$10,200/yr salaries tax savings (at 17% marginal rate). · Eliminates dividend fulfillment ratio uncertainty on the monthly annuity stream. | Available in both HKD and USD with identical published IRR bands across issue ages, gender, and smoking status. · Projected total IRR up to 4.22% (USD) ranks toward the upper end among Hong Kong bank-channel QDAPs. |
| Watch-Outs Before Deciding | Non-annual payment modes cut guaranteed IRR noticeably (e.g. 2.70%–2.94% on 15Y vs. 3.10% annual); pay annually if cash flow permits. · Shares the HK$60,000 annual deduction cap with MPF TVC — avoid over-allocating beyond unused tax headroom. | Spread between guaranteed IRR (0.94%–1.65% HKD) and projected total IRR (3.82%–4.02%) exceeds 2.3% — always stress-test at 60%/80% fulfillment. · If weak markets cut non-guaranteed bonuses by half, realised IRR can finish well behind BOC Life Fixed Term's 3.10%–3.30% guaranteed floor. |
Sources
- BOC Life: Deferred Annuity (Fixed Term) Official Product Brochure PDF (BOC Life, Last verified: 2026-11-20)
- HSBC Hong Kong: Deferred Income Goal Brochure PDF (June 2024) (HSBC Life Hong Kong, Last verified: 2026-11-20)
CoverHK · BOC Life Fixed-Term QDAP vs. HSBC Income Goal QDAP: Hong Kong Bank Annuity Showdown
Want a tailored clause check or exact numbers?
Share your age band, existing corporate medical cover, or current MPF trustee — we will reply in writing with a clear side-by-side summary.